Pages

Monday, September 23, 2013

SGX Stocks Starter Kit


The image above shows a starter kit provided by myself for initial investments of up to $25K. The rational for this starter kit is to help people who do not know about investments to get started with some of the good stocks i've picked up over the years.

A diversified portfolio helps an individual to hedge against risks across different sectors. This starter kit will help to kick start a fresh equities investor and journey him to finding the best mix for himself in future, with good returns yet protect against the downfalls of the stock market.

*note: Invest at your own risk. I will not be responsible for any of your loses or winnings.

Sunday, September 22, 2013

Cheap outdated electronics caused by QE

With the continuation of quantitative easing in the US, inflation as a whole will rise and that will force growing countries in Asia to strengthen their currencies against a weaker USD.

Food prices, fuel prices will rise as well as transportation costs. The medium income group which i call the savers group will be badly affected by this.

On the other hand, the IT geeks are able find great bargains from IT products as the electronics sector are facing an overwhelming supply of products in the market. Technology companies compete very fiercely to innovate and push out better products.

Consumers, on the other hand are also sitting on the addiction to upgrade their products. The electronics second hand market is facing a problem of over-supply and people are all-time ready to sell their second hand electronics to upgrade to a better model.

The second-hand markets are filled with bargains or cheap electronic products as people seeks to upgrade their model.

There could be other sector that may be affected by this, by i think the most visible market to me is the electronics market.


Friday, September 20, 2013

SGX breaking into the China Market

SGX yesterday announced that it had signed a memorandum of understanding with the Bank of China to develop RMB products and services and expand the exchange business in China as well as helping the Chinese to expand their products in Singapore.


Singapore is a small country and it is tough for SGX to grow its securities and derivatives business in the region. Given the largest population country like China, SGX is able to leverage on the population numbers to better grow its business. 

Furthermore, companies in China still lack good corporate governance and locals seeked to park their cash elsewhere. SGX, as Geoff Howie, market strategist at SGX, explains that SGX remains one of the most diversified exchange in the world perfectly caters for the people in China, who are in search of companies with better corporate governance and good returns on investments.

Fed Delay Taper, So what's next for the market?

Fed's decision to taper was because unemployment rates were still high. However, cheap money does not seemed to flow to where it is suppose to flow. According to Bloomberg, the QE saves companies such as Verizon, Apple and other companies about $700Billion in interests payments. However, it does not seem to effectively bring the jobless rate down.

What is seen is that stock markets are rallying and companies are able to lend cheaply to expand business. This can lead to a bubble when some companies spend the cheap loans on bad investments, and later not being able to pay back. Another scenario can be as such that companies took advantage of the cheap loans to borrow excessively, without concerns of being able to pay back and when interest rates hike, these companies default on their payments.

These two scenarios are likely to bring about a great correction like the Lehman Brother's bankruptcy back in 2009. And this time it could be bigger because this time the target audience are companies instead of the local public. The companies with good management and strong cash flow will inevitably benefit from the QE in the long run.

Therefore, right now the good investment opportunities lies in the US.

What about Singapore stocks? 

The cheap money continue to flow into Asia by spurring US companies spending and currencies has to be strengthened to control inflation growth.

Stocks will likely to grow at a slower pace, as spending power is dispersed within the Asian region. I expect to see healthy and steady growth in the Singapore stocks. STI could go up to 3,300 this year, but looking ahead, tapering could set in a major correction in the stock market. Now is a good time to offload stocks which are heavily in debt, and then buy back when STI retreats to 3,000.

Companies with solid fundamentals and remains low and or zero debt position will bear sweet and juicy fruit in the long run.

Source: http://www.bloomberg.com/news/2013-09-17/bernanke-saves-companies-700-billion-as-apple-to-verizon-borrow.html

Tuesday, September 10, 2013

Hafary paying out 29% dividend


They supply flooring tiles to the Singapore market by importing from manufacturers located around the world.

Such companies do not produce good cash flows, but this time they are paying out a dividend yield of 29%. Such a huge payout may not be sustainable for the company to grow healthily, but if they are able to consistently grow, then i think it is an attractive bet.

But for now, markets are cautious about the bond tapering which is expected to happen this month. I will be cautious about it too because when markets fall, fundamentals will not work on those who deal in large volumes.

Friday, September 6, 2013

SATS, stable recurring income

SATS two main stream of incomes lies in its gateway services and food solutions.

Its gateway services operate in Changi Airport and Marina Bay Cruise Centre which are the 2 major tourist stopovers.

Their food solutions served mainly the Airline catering and also SFI, which feed the soldiers in Singapore every day.

These 2 businesses experienced high daily traffic and deemed to supply the company with stable recurring income in the long run.


Wednesday, August 14, 2013

Sgx on google finance

Sgx had finally listed their counters on google Finance which is excellent for the business as it is able to attract more global participation.

Sgx had quietly been growing it's business for the past few years and is slowly reaping better net margins.

It has also managed to attract China investors by introducing RMB currency in one of the its counter.

Prices had gone up for sgx after hitting its low at 7. Nevertheless, as it increased it dividend payout over the years while maintaining a zero debt position, it will be one of the safest blue chip to acquire.

Sunday, August 11, 2013

Growth in China's food consumption

I spent my last long weekend in China town today. The crowd consists of mostly tourists with restaurants charging a premium for tourism eats, and stores selling China souvenirs ranging from Chinese paintings to calligraphy brushes and signature stamps made from jade.

Indeed the place really looks like a mini China, with all sorts of China-related products and also the shop houses were well preserved to bring out a historic look.
Since i came back from my China exchange in Beijing back in 2008, i had never tasted food that I tasted in China until i came across a Chinese food shop house. Looking at the amount of food the people ordered and the tongue curling accent, it appears that the place was operated by a native chinese. 
I ordered some pork belly and beef bbq sticks and they tastes exactly like the ones in China. Very tender and tasty with flavoring powder added to them.
It was a great meal and my stomach was filled to its brim. The price of the food was reasonable and the portions were more than what i expected.
Now going back to the growth in China's food consumption, the people dining over at the restaurants have big appetites because i see them ordering a lot of food. The fact that almost all the customers in the restaurants had filled up the dining tables tells a little bit about the pace of food growth in China.
In fact, back in 2008 when i was in China, people also ordered food generously especially with friends or family. 
The food is spicy and sometimes oily, and beer(Tsing Tao or Harbin Beer) goes along well with their food. 


About 2/3 of their food comprised of vegetables which were used to add into dishes as flavourings or purely vegetables for consumption.
There is a china listed stock which produces vegetables and markets to Asia, Europe and US. Trading at a PE ration of 3.8 and net Book value of 0.7 gives a stock a very good value. However it had yet to pay dividends to shareholders, but the price of vegetables will increase given the rising food consumption, and also the lack of farmers in China as more people in the village seeks to urbanize in developed cities in search for a better life.  

Below is the products produced by China Minzhong: 


Wednesday, July 24, 2013

Shareholder's member card

"As a token of appreciation for the continued support of our valued shareholders, the Board of
Directors of the Company is pleased to announce that the Company will be giving a Privilege Card
(the “ST Card”) to its shareholders. The ST Card shall entitle the shareholders, their family members and friends to a special room rate and 10% discount on food and beverage at our Nantong and Suzhou hotels.

Hotel Room Type Rate

Nantong Santeh Hotel Deluxe Standard Room with breakfast for one RMB410 per night
Suzhou San Teh Hotel Superior Standard Room with breakfast for one RMB398 per night

Shareholders whose names are registered in the Depository Register and Register of Members of the
Company as at 5.00 p.m. on 31 July 2013, including CPF investors will be entitled to the ST Card."


This is the first of such initiatives i've seen to provide shareholders with benefits.


Friday, July 19, 2013

Cheaper Suntec REIT, but is it worth buying?

Source: bloomberg

Suntec REIT currently have a NAV of $2.03 and priced at $1.53 on 20 Jul 13, Fri. However, gathered sources reveal that it had one of the most expensive management fees in SGX REIT section, and also had stopped receiving income support for its One Raffles Quay (ORQ) property. Management blamed the 4.7% fall in DPU on the partial closure of Suntec Mall and Suntec Singapore for enhancement works.

Source: http://www.todayonline.com/business/suntec-reit-posts-47-fall-q2-dpu
Source: http://infopub.sgx.com/FileOpen/Suntec-2Q2013-Presentation.ashx?App=Announcement&FileID=248407

Suntec REIT might be affected by the possible hike in interest rates in the future, However, with the basket of good portfolio assets, it may become profitable in future when its Suntec assets reopened fully and is able to extend the lease of the current office tenants which lease is set to expire in 2013.

Apart from that, it is also able to benefit from the increasing office rates, especially in key CBD areas in MBFC and OFQ


Friday, July 12, 2013

Manipulating the stock market

Ben Bernanke had once again manipulated the markets with his speech on continuing the $85M monthly bond purchase which he previously hinted a possible tapering in purchases.

Stocks across the world rallied on the comment, but despite the rally, the euro zone crisis is still not over and interest rates are quietly rising.

Source: http://www.forbes.com/sites/robertlenzner/2013/07/12/how-bernanke-manipulates-the-markets-in-3-easy-steps/

I still think that there are downsides to the market sometime around mid 2014 due to the forecast of bond tapering by Bernanke and markets will still continue to be on the uptrend for the next few years due to inflation caused by bond purchases.

Banks are a good bet against rising interest rates and stocks with low borrowings as higher interest rates affect profit.


Friday, July 5, 2013

Investing in SGX

There had been much volatility in the stock market this week and stocks were moving up and down in anticipation of the Fed's announcement to the tapering of bond purchases in the US.

Portugal's economy was left in a mess when two ministers resigned from coalition government. Stocks around the world plunged in reaction to this incident, causing more uncertainty looming in global equities.

I was prepared for a crisis, seeing SGX plunged from a 6 months high of $7.8 to $7.03 on 28 June 13. And furthermore SGX, reported higher revenue and net profit amid a 10% drop in price. A 10% drop in price does not justify the strong performance of SGX, which is the sole leader of equities and derivatives products in Singapore.

Source: Bloomberg


Thursday, June 20, 2013

Genting SP in a difficult position

S$9Billion in debts (bonds) + S$2.5B secured loans

Their total debts make up to about 11.5B. and they managed to pay back S$122M first quater this year and at most S$488M this year.
They are still left with S$10.512B of debts to repay plus bonds interest payout of 5%, which make out to be about S$45M per quarter.

To hold or sell will be your choice to make. Good luck :)


Correction underway

Embrace the bear and enjoy the ride later!

Wednesday, June 19, 2013

Very unpredictable market

The recent drop of STI suggests that investors are taking a very cautious approach to the reduction of QE by the Fed, ignoring fundamentals of good stocks which are making money as stated in their financial report.

One thing for sure is that the next announcement by Ben Bernanke will affect the market movements on the direction of further QE.

If the Feds decide to stop QE, the market is pretty sure to hit the bear stance and start dropping as most investors will anticipate a huge drop in the market. A Ben Bernanke's exit may direct markets as well.

Fund managers are on standby with cash to seize the great opportunity when the markets start dropping.

Hope i have enough cash to size the opportunity, so can you. In the meantime, be cautious with stocks and hold some cash for the GSS.

Good luck people :)


Tuesday, June 11, 2013

STI down! Don't panick.

The STI had been performing badly these few days and a lot of red numbers are coming up from the SGX website.

US was upgrade to stable by S&P, and Japan upgrades its economic outlook.

Source: http://www.reuters.com/article/2013/05/20/us-japan-economy-report-idUSBRE94J00S20130520

Source: http://money.cnn.com/2013/06/10/news/economy/sp-u-s-credit-rating/index.html

Both of them are good news but despite that, it still is not able to push up the markets. At current situation when the market is selling, most people out of fear, will start selling as well.

"The market is there to serve you, not instruct you" as stated by Warren Buffet.

Be determined and stick to your decision.

Good luck


Tuesday, June 4, 2013

Bears are tired while Bulls attack

The Straits Times Index dropped from a 5 year high of 3600 to 3300 in two week period. Blue chip stocks like ST Engineering and GLP see some fluctuation in stock prices. However, the tide is turning around with some good news.

Spain's economic position improved as it sees better export numbers.

Source: http://www.bloomberg.com/news/2013-06-03/spain-s-crisis-fades-as-exports-lead-the-way.html


This correction period could be a good chance for investors to buy stocks. A further bull run in future may occur as interest rates around the world remain low. 

Good luck to all investors.

Tuesday, May 28, 2013

Azeus Systems, a hidden pot of gold


This company just reported strong profits in its FY2013. The jump from FY2012 was 199%, which reflected strong performance of the company.

It is going to issue out about 12.5% dividend yield to shareholders this financial year, which is very attractive for shareholders.

However, the problem with this company is that it lacked analyst reports on the stock, and many people are not aware of this stock yet.

Its main currency is in HK and they are an IT solutions provider, mostly for the Hong Kong government departments. They deal mainly with maintanance and support contracts and several large scale software development projects.

I'm buying this stock tomorrow. My advice to you is to recognize this stock before the market do. :)

Sunday, May 26, 2013

Dilemma in choosing a stock to sell

Last week i bought XMH holdings, and realised that i ran out of cash because for the past few days i was constantly purchasing stocks.

There was a dilemma in choosing what stocks to sell since most of my purchases are for long time holding. Then i started reading financial statements on some of my stocks which i recently purchase to fund my XMH holdings.

I read MTQ corp financial statements and realized that they are on average debt levels with $73M debts and $40M cash holding, about 1.8 times.

Swissco Holdings, although have some good future growth prospects but their debts was bad at about 6 times their cash holding. They are in a riskier position as they do not hold enough cash to pay back the debts when the need arises. And furthermore, they reported weaker earnings in their latest results.

Ezion was bad with debts with about $706M in debs and $148.5M in cash, which is 4.75 times their cash holding.

Companies with higher debts reflect that they need much more money to generate better revenues or better profit margins which may put the company in a riskier environment in an event of unforeseen circumstances. And furthermore, debts reduces shareholder value as the shares contain more debt than assets.

I arrived at a conclusion and sold both Ezion and Swissco Holdings.


Friday, May 24, 2013

Comfort Delgro, a comfortable one indeed


A global transport company with major operations in Singapore, as well and UK and Ireland, Australia, China and minor operations in Vietnam and Malaysia.

ComfortDelGro has expanded significantly and now operates in seven countries and has a global fleet of about 45,800 vehicles.

ComfortDelGro’s businesses include bus, taxi, rail, car rental & leasing, automotive engineering services, testing services, driving centre, insurance broking services, outdoor advertising and car dealership.


Below in their FY2012 financial highlights and they are growing decently throughout the years. 

  The graph above highlights their successful growth track record since 2008. This stock is a good stock to own despite the recent drop of $0.255 due to the sell down of major share holder, Singapore Labour Foundation.

This could mark a decent opportunity to buy into the stock and hold it forever.

Thursday, May 23, 2013

Stocks will go up in the next 10 years


“As price of risk assets improve, there are more pressures and temptations to reach out,” said Lim, 42, who previously oversaw GIC’s investments and relationships in Europe, Africa and the Middle East.
“Though valuations are not low currently, longer-term prospects are not to be missed,” he said.


Source: http://www.bloomberg.com/news/2013-05-21/gic-says-returns-on-stocks-and-bonds-to-lower-in-next-10-years.html

Although stock prices are not low at the moment, but quantitive easing in Japan and US as well as low interest rates around the world are spurring companies to grow and may cause a slight recovery in the global economy.

Some companies may still lack behind, but there are still opportunities present with the current high valuations.

Let me share with you one of the factors of growth in the oil and gas industry.

the Obama administration apparently supports the expansion of the natural gas industry and the controversial technology of hydraulic fracturing.


Source: http://communities.washingtontimes.com/neighborhood/climatism-watching-climate-science/2013/may/22/obama-administration-supports-fracking-and-natural/

From Hiap Seng's 3rd Quarter FY2013:

The outlook for the oil-and-gas and petrochemical industries which the Group serves still remains
positive.

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_17CFF9306C301F2248257B0B0027D0D2/$file/HS_Q3FY2013_results_announcement.pdf?openelement


From MTQ's FY2013 ended 31 Mar 13:
Conditions are expected to remain buoyant in the oil and gas industry.


Both these companies have great opportunities for future growth. Hiap Seng recently announced a joint venture with KUB Builders to bid for the Petronas Rapid Tank Farm Project in Malaysia.


MTQ Corp, which reports doubling of pre-tax earnings in Q4 FY2013, complained of overwhelming demands from Bahrain.

Sunday, May 12, 2013

Fearing a correction? Go for small caps


Stock markets are soaring and are mostly driven by countries printing money or cutting interest rates in an effort to spur growth in the economy. However, some rises are not justified by fundamentals, therefore are vulnerable to correction. Although there are many overpriced stocks being overbought but some of the low volume small caps stocks are still undervalued and not overbought yet.

This is a period when companies are releasing their results and some of the companies are reporting significant earnings but have not risen in value.

My advice is to take a look at the results and seize the opportunity before the markets realized them.
Stocks like Singtel and Starhub are likely to correct, especially Starhub which had been constantly rising in value.

Thursday, May 9, 2013

MTQ Corp and Ezion, the rapid growth of the oil and gas industry

MTQ Corp FY2012 net profit surged 148% as compared to FY2011 while Ezion's net profit surged 227%


Ezion's report in the next 12 months:

The Group expects more Service Rigs to be deployed in 2013. The Group is also expected to enjoy higher
revenue from Australia with the commencement of the APLNG and GLNG projects in 2013. Leveraging on its track record, experience and existing business infrastructure, the Group will continue to pursue business
opportunities to support LNG related projects in Australia and its vicinities. The Group will also continue to focus on investment in Service Rigs to meet the strong demand from its customers in the oil and gas industry.
Barring any unforeseen circumstances that may arise to destabilise the current financial market and global
economy, the Group expects to perform better in the financial year ending 2013.
 
MTQ Corp's report in the next 12 months:

Conditions are expected to remain buoyant in the oil and gas industry. With a wider geographical presence and a much broader suite of subsea and engineering services to offer, the Group will continue its strategy to strive for organic growth and benefit from the buoyant oil and gas industry.

MTQ also acquired Neptune Marine Services at a discount of A$6.4M.

Their total Equity for Half Year Results Dec 2012 is about A$64M after deducting accumulated losses and their takeover bid is A$57.6M.


Sunday, May 5, 2013

Evolving Stock Market

Since the 2008-2009 stock market crash, the market have been moving with a lot of uncertainty. Sentiments of a stock market crash have been underway since 2012 and there are fears in investing into equities.

After a report by Jim O'Neill saying that it makes sense for central banks to own equities, the stock market has already been on a bullish path. He also added that many sovereign wealth funds which are tied to central banks have already invested in stocks.

Source: http://www.cnbc.com/id/100674247

The increased in liquidity could probably explains why stocks are rising. And the reason why equities are preferred rather than commodities is that they give dividends to shareholders while holding on to commodities like silver and gold doesn't provide any returns on investment.

Stock prices also indicate an improving economy in the U.S. and the rest of the world as companies report better earnings.


A visible pattern can be seen in the current stock market that seems to be different from how it was in the 2008 stock market crash.

The increased liquidity injected into equities are more fluent and steady in a way that is more evenly distributed. Stock markets are less prone to over-heating as previously stocks are blindly bought with "free cash flow".

Rising equities can be seen as inflation and banks and economies developed better counter-measures for overheating. Singapore currency went up against the USD to counter overheating. The Japanese Yen weakened together with the USD and drives exports in both Japan and the U.S. Asian countries like Singapore, welcomes "cheap money" in the stock market, which explains the rise in equities. 

Back in 2008, the crash seems to be engineered in a sense that the media and the rating companies were reassuring the public to stay invested when the fundamentals are not in place. However, now the rising bubble seems to be more cushioned thanks to mistakes in the past and also indicative of a slow global economic recovery. But that said, rating companies like S&P and Moody's rating cannot always be used as indicators as they might be able to engineer a certain outcome. 

From 
to 


Friday, April 26, 2013

Hyflux, the next big thing?


Hyflux have faced stiff competition in the water market. They specialised in Seawater Reverse Osmosis(SWRO) plants which due to high expenses, may not be the most preferred choice.

However, Hyflux did not give up hope on the China market, which it seen to contain huge potential to its business, managed to sign two memoranda of understanding (MOU) in China.

"Hyflux said in a statement it had signed two memoranda of understanding (MOUs) with the governments of Chuxiong and Qujing.
The total investment value is estimated to be around 1.2 billion yuan (S$240 million) for the projects in Qujing and less than 2 billion yuan for the projects in Chuxiong.
The projects covered under the MOUs include developing water recycling, wastewater treatment and potable water treatment plants."

The table below shows that other companies are able to penetrate China better than Hyflux. The major revenue from Hyflux is from Singapore.

Source: http://www.sharesinv.com/articles/2012/03/02/can-hyflux%E2%80%99s-tap-continue-to-flow-beyond-the-home-turf/

Hyflux generally has grown in terms of revenue and net profits but however, despite the high expenses and competition from the water industry, the outlook for Hyflux doesn't seem very favourable. Furthermore, the issuance of preference a few years back with the guaranteed returns of 6% may give Hyflux a tougher time to refinance or buy back the debts.

Hyflux's high debt position remains a challenge to its future. Once the Tuas Desalination Plant in Singapore is operational, Hyflux may see a brighter light with more profits coming in from Singapore. With adequate funding, Hyflux may be able to better finance its debts and grow healthily.

A "HOLD" rating will be given due to high debts and expenses incurred by Hyflux.

Sneak peak at the Telecom Sector

Generally, telecom sector stocks like Starhub, Singtel and M1 have grown quite well in the recently. Let's look at their performance for the past 6 months.

Starhub increased from 3.68 to 4.35 in the last 6 months, up 18%

M1 Ltd, owned by Telecom Giant Axiata Group Berhad went up from 2.61 to 3.17 in the last 6 months, up 21%.

Temesek Holdings owned Telco, Singtel, went up from 3.21 to 3.77 in the last 6 months, up 17%. It last announced to set up a subsidary into the newly open economy, Myanmar but still pending for further updates. Myanmar could be seen as a major growth benefactor for singtel


Wednesday, April 17, 2013

Corporate Rating for Thai Bev


Standard & Poor had remove Thai Beverage from its credit watch. Its rating had also been changed from BBB to BBB- with negative outlook.

According to S&P website:
‘BBB-‘—Considered lowest investment grade by market participants.

The first reason was due to the high cost of the F&N acquisition which amount to about US$11.2Bn. The company debts are expected to remain high and cash flow to remain adequate. 

The second reason was that TCC Assets hold about 61% of F&N and no plans were known as to how the debt will be financed.

With that being said, F&N still remains strong in its beverage sectors owning 100 PLUS, Fruit Tree, Seasons and Ice Mountain.

Drinks made up majority of profits in coffee shops and will continue to grow because people will need to quench their thirst. This stock poses strong upside potential and will possess the financial strength to handle the debts.

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_901BDC35F61B0FFB48257B4A004547E9/$file/Corporate_Rating_by_SP.pdf?openelement

Source: http://blogs.wsj.com/deals/2013/04/12/thaibevs-fn-deal-prompts-credit-rating-downgrade/

Wednesday, March 27, 2013

Olam in danger?


I've a friend who bought this stock and i was a little speechless because since he bought it, wouldn't be a good idea to pour hot water on him. But i try to put it in a polite manner, "Well, have you read its financial reports? Do you have good understanding of its business operations?" And he said, "Not really but since it dropped quite a lot since last week, looks like a good buy so i bought it". And the fortunate thing is Temesek Holdings was willing to support their rights issue during that period and he managed to sell it for a decent profit. I was glad for him.

Not that i knew a lot about Olam but looking at the financial report, it kind of make me uneasy. Below is the financial statement for the first half ended 31 December 2012.

Both figures which are highlighted in red indicates the revenue and net profit respectively. In short, Olam has revenue close to about $9.6bn. However, after deducting the expenses, the company earns close to $200m which translates to about only 2% of revenue. This looks crazy to me because the company incur some pretty dangerous operation costs.

Below shows the their borrowings which have grown 15-30% from last year to this year(bad indicator).
Moving on to the financing activities for the company, the only thing i want to highlight here is that there is no indication of them paying off debts, which is one of the most dangerous parts that normal investor will not be able to see. Their debts are increasing, and yet they are having trouble paying them off.


In summary, this company is in trouble but some people are still betting their money on it. Let time decide if this company will survive and make it. I highly doubt this company will ever be profitable in this current state.

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_022449932FC2A5F648257B0B002FE6CA/$file/7Feb2013-H1FY2013_Results.pdf?openelement

complicated business, Capital Land


For 3 years of my investment experience, i have never read about capital land's financials or even think of investing in this company, not because it doesn't look attractive but rather i do not know the valuation of the company. Their assets are very broadly scattered and thus, is difficult to know or understand the nature of their businesses.

Lets take a look at Capital Land:

Capital Land had tried to reduce their debts but even after its bank borrowings and issurance of debt securities, they are still negative of about $680m on cash flow.

There are no clear indications of how the investments will generate high returns but their debt level doesn't look good.

Although their Net Asset Value(NAV) is close to its buy price, the PE ratio of 16 indicated that the earning potential of the company is still not fantastic, or rather they have not reap what they sow yet.

An image of Capital Land's cash flow statement:


Saturday, March 23, 2013

These are some factors to consider when buying a stock


For this post, i will quote the example from Swissco Holdings FY2012 financial statement.


Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_7E3838BAE920403448257B1E0033133B/$file/FY2012SHLYearEndAnnouncement_26Feb13.pdf?openelement


  • Repayment of borrowings > Proceeds from borrowing (both in 2011 and 2012)
  • Net increase in cash and cash equivalents (both in 2011 and 2012)
When the repayment of borrowings amount is more than the proceeds from borrowing means that the company is able to generate more cash from previous borrowings to reduce its debts. It is good for the shareholders because it allows shareholders to own more assets than the company's debts.

Below is the image showing the Net Asset Value(NAV) per share. When debts are reduced, NAV will increase.


The net increase in cash and cash equivalents also reflected positively on the company's performance as it is able to generate more cash than expenses.


Friday, March 22, 2013

Opportunites in 4th runway in Changi

SINGAPORE - Changi Airport is studying the need for a fourth runway to cater to more flights in the coming decades, even as plans are finalised for a third landing and take-off strip.

The Civil Aviation Authority of Singapore (CAAS) is seeking consultants to look into the feasibility and benefits of a fourth runway, The Straits Times found out.

Source: http://news.asiaone.com/News/Latest%2BNews/Relax/Story/A1Story20130321-410381.html

The rapid expansion of the aviation industry leads to many investment opportunities which lie ahead. The first and upcoming is the seletar aviation hub which will be completed somewhere in 2014.
Below is the location map from JTC.


The Seletar Aviation Bub seeks to reinforce Singapore as a major hub for aerospace and will attract more companies to expand their aviation capabilities. Their strategy to is also supported by the projected strong growth in Asia’s demand for business jets (expected to grow 6-9% per annum over the next five to ten years). A slow but constant growth.


JTC Corporation said these companies stand to benefit from many synergies resulting from an integrated environment and the close proximity to suppliers and partners.Aerospace companies to benefit from synergies at Seletar Aerospace Park.


Stocks to benefit

As Singapore position itself for the aviation growth, the demand for in-flight catering services as well as gateway services will increase. 

SATS, SIA Engineering, ST-Engineering


At Singapore Changi Airport, SATS handles 80% of scheduled flights and serves about 50 of the scheduled 68 airlines out of Singapore. With constant innovation and a growing network of partners, SATS offers a suite of value added services integrating knowledge, specialised skills and ample resources to meet the needs of this industry.
Source: http://www.sats.com.sg/SolutionsandServices/ByIndustry/Airline/Pages/Airline.aspx

ST-engineering revolves much around Singapore's military capabilities. One of such benefits will be the allowing up to 4 of the new Littoral Combat Ships to dock in Changi Naval Base by Singapore. Although this only will contribute a portion to the ST-marine arm, but ST-engineering as a whole, is able to grab military contracts from around the world, thus proving to be able to constantly generate revenue for the company. 

Below are 2 military contracts won by ST-Engineering this year:
  • Construction of 8 RSN patrol vessels by MINDEF (30 Jan 13)
  • ST ENGINEERING’S AEROSPACE ARM SECURES C130 CONTRACT FROM ROYAL AIR FORCE OF OMAN (15 Jan 13)
Source: 


SIA Engineering, positioned in Changi will be one of singapore's top spot for (MRO) when Changi airport expands. The planning of the 4th runway is an indication that provide vast opportunities for SIA Engineering which is the main (MRO) spot in Changi. 

4 reasons why SIA Engineering is still on industry's top spot

Monday, March 4, 2013

The dragons are sleeping, Dukang Distillers

Investment risk associated with Dukang

  1. Government regulatory controls
  2. Cessation of substantial shareholders over the past three months
  3. Slumping prices for Moutai and Wuliangye products


Source: http://www.sharesinv.com/articles/2013/02/05/dukang-distillers-%E2%80%93-still-growing-despite-industry-headwinds/

Saturday, March 2, 2013

Kori Holdings


Specs

PE Ratio: 4
Net asset value(NAV) per share: $0.35
Closing price on 1 March: $0.35

Their established track record and strong technical expertise for both structural steelworks and tunneling works has allow them to compete effectively with other industrial players. Their outlook will remain positive given the Building and Construction Authority(BCA) has projected S$26 billion to S$32 billion of construction demand for year 2013. They are confident of  winning the contracts from the upcoming Thomson MRT Line.


Potential Projects
  • Singapore
  • Malaysia

GOVERNMENTAL SUPPORT FOR INFRASTRUCTURAL 
DEVELOPMENT IN MALAYSIA
• Under the 10th Malaysia Plan, an economic blueprint that covers 
2011 to 2015, the Malaysian government has allocated 60% of 
RM230 billion for physical development
• Projects underway include the extension of an electrifi ed 
double-track railway project to Johor Bahru, the construction 
of a mass rapid transit system covering a 20km radius from the 
Kuala Lumpur city centre and the building of a new low cost 
carrier terminal at Kuala Lumpur International Airport
As at the Latest Practicable Date, the order book for the structural 
steelworks and tunnelling services business stood at approximately 
S$82.8 million, which would translate into revenues for the Group 
over the next one to three years.

GROWTH IN SINGAPORE’S INFRASTRUCTURE
• As the population and number of tourists and immigrants 
increase, the government will continue to see a need to raise its 
spending on projects for further infrastructure development
• These will include the need for more housing, transportation 
infrastructure and industrial facilities


About Kori Holdings
The Company was incorporated in Singapore on 18 May 2012 under the name of Kori Holdings Pte. Ltd. The Company was converted into a public limited company and changed its name to Kori Holdings Limited.

The Group is a Singapore based multi-discipline engineering and construction services company. The Group's principally engaged in providing civil/structural engineering and infrastructural construction services as a sub-contractor for commercial, industrial and public infrastructural construction projects. Its customers include local and overseas developers in the engineering construction industry.

The Group’s businesses can be categorised into two main segments as follows:
• structural steelworks services; and
• tunnelling services.

Source: SGX

Friday, March 1, 2013

Nice things coming


Thai Beverage reported a 145% jump in net profit in their FY2012 results. The outstanding performance could be attributable to their F&N acquisition which was instrumental in expanding their distribution networks in Asia.

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_3295A55B8DD2A4AB48257B1F0034019D/$file/YearEnd_2012_SGX_Format.pdf?openelement


Starhill Global REIT announced the completion of acquisition of Plaza Arcade in Perth which was strategically located next to their owned David Jones Building. Their Perth operations has expanded and their strategy followed similarly to Singapore's.

Similarities in acquisition strategies

Australia - Perth

  • Plaza Arcade
  • David jones Building
Their Perth operations are strategically located at the center of the city with a 200m radius from their financial hub, government house, Australian Bureau of Statistics, Hotels and 500m SW of Perth Convention and Exhibition Centre.


Singapore - Orchard

  • Ngee Ann City
  • Wisma Atria

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_79D8F2FBE72646DA48257B210014737A/$file/PlazaArcade130301.pdf?openelement


Silverlake Axis won new contract with Hong Leong Bank, Malaysia to implement Enterprise Payment Platform which will transform and modernize the banks's existing payment system into a centralized enterprise payment system with advanced intelligence workflow designs.

This deal as stated in the news realise, will contribute positively to the current and following financial year.

Source: http://info.sgx.com/webcoranncatth.nsf/VwAttachments/Att_B59271BFD80F5D7248257B2100375DAC/$file/SAL_HLB.EPP.Announcement.pdf?openelement

Tuesday, February 26, 2013

Good Buying Opportunity

GLP confirms GIC's stake sale to rebalance portfolio.The Business Times had earlier reported that the sovereign wealth fund is planning to sell a 12.5 per cent stake in GLP for up to S$1.6 billion.

GIC reduced its stake to about 36.8% from 48.9%, according to one source.


This pose a good opportunity to purchase the shares at a lower price given its strategic positions located in Japan, China and Brazil, which according to GLP CEO Ming Mei is a fast-growing but under-served market with compelling opportunities for future growth.

This early entry into Brazil might prove advantageous when more demand for modern logistic facilities arise from its commodity exporting nation.

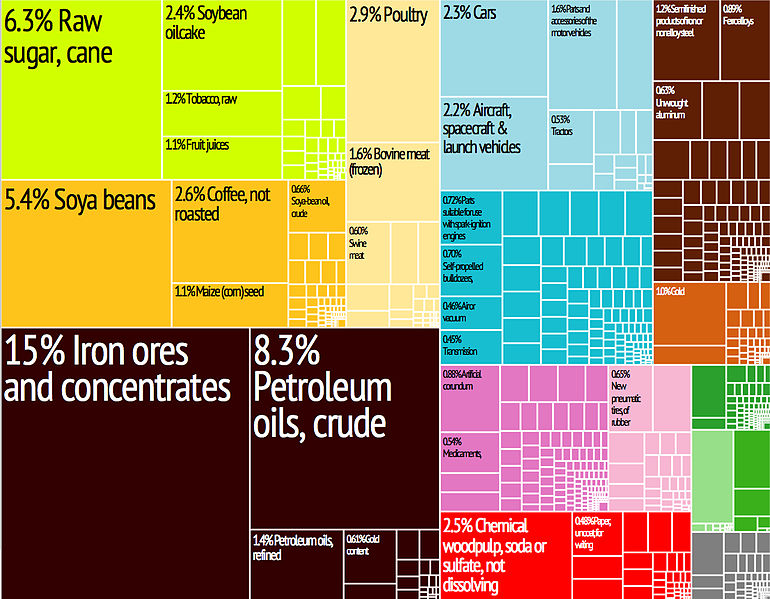
Graphical depiction of the country's exports

The picture clearly explains the Brazil economy and its capability of exporting commodities and logistics remain one of the key elements to support its growing economy.